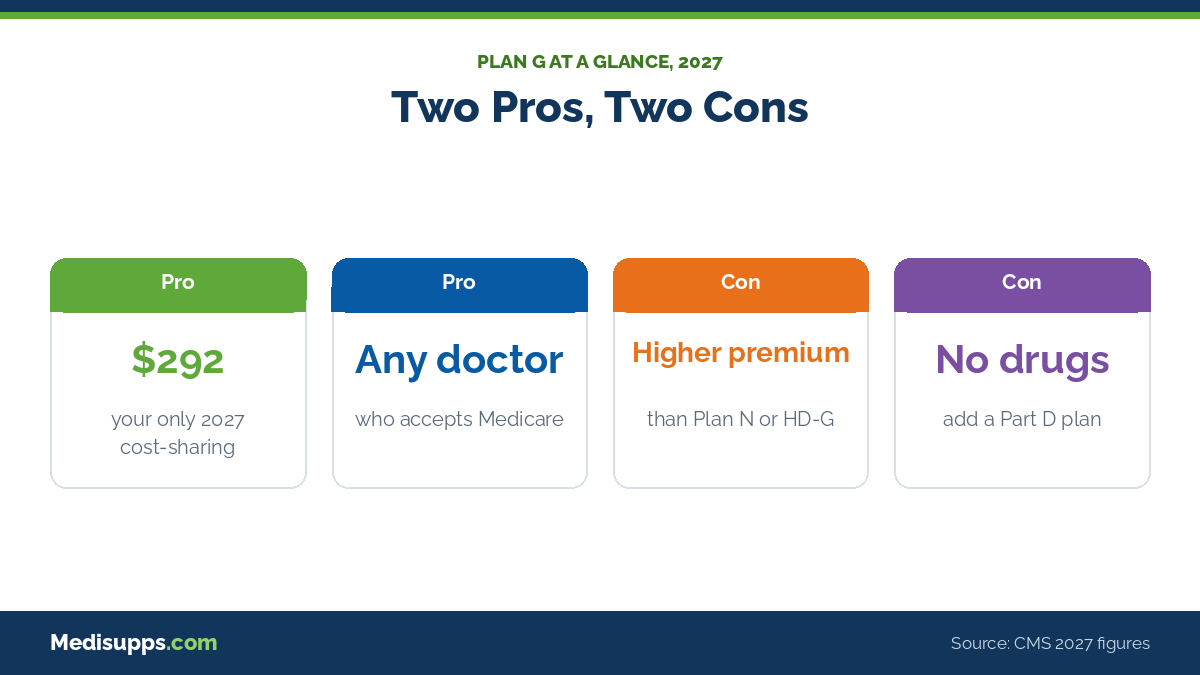
The main pros of Medicare Plan G are near-total coverage and predictable costs: after the $292 Part B deductible in 2027, it pays every remaining Medicare-approved cost, and it works with any doctor in the country who accepts Medicare. The main cons are price and gaps it was never designed to fill: Plan G usually has a higher premium than Plan N or high-deductible G, and it does not cover prescriptions, dental, vision or hearing.
Weigh the price side
See Real Plan G Premiums for Your Age and ZIP
The biggest con of Plan G, its price, varies widely by company.
Rates and plan availability vary by state, age and insurance company.
Whether the trade is worth it depends on numbers, not slogans. Below we weigh each advantage and drawback of Medicare Supplement Plan G, then test them against real January 2027 premiums from Maryland’s state rate guide.
For the full list of plan letters and what changed this year, see Medicare Supplement plans for 2027.
The short answer
Plan G is the most complete Medigap plan a new enrollee can buy, and its only cost-sharing is the $292 Part B deductible. Its downside is a premium that can run hundreds of dollars a year above Plan N.
Plan G in 60 Seconds
Plan G is one of the standardized Medigap plans sold by private insurance companies to people with Original Medicare. Since Plan F closed to anyone who became eligible for Medicare on or after January 1, 2020, Plan G has been the fullest plan most new enrollees can buy. Federal law fixes its benefits, so a Plan G from one company pays exactly the same claims as a Plan G from another.
- Pays the Part A hospital deductible: $1,776 per benefit period in 2027.
- Pays Part B coinsurance, usually 20% of the approved amount, after the deductible.
- Pays Part B excess charges, up to the 15% doctors who do not take assignment may add.
- Leaves you the Part B deductible, $292 for 2027.
The Advantages of Plan G
Coverage you can budget for
With Plan G, a heart surgery, a cancer treatment year or a long hospital stay costs no more out of pocket than a routine checkup year, once the deductible is met. You do not need to read a copay chart or guess what a specialist visit will cost.
Plan G also avoids most surprise bills. Because it pays excess charges, a doctor who does not accept Medicare assignment cannot leave you with the extra 15% that Plan N would.
The Drawbacks of Plan G
| Drawback | What it means for you |
|---|---|
| Higher premium | You pay for full coverage every month, whether you use care or not. |
| Part B deductible is yours | $292 in 2027, and it usually rises each year. |
| No drug coverage | You need a separate Part D plan for prescriptions. |
| No routine dental, vision or hearing | Medigap follows Medicare, which does not cover these. |
| Premiums rise with age at many companies | Attained-age policies go up as you get older, on top of yearly increases. |
| Hard to switch later | Outside your six-month Medigap open enrollment period, most states let companies ask health questions. |
Plan G benefits are the same in every state except Massachusetts, Minnesota and Wisconsin, which use their own standardized plan designs.
The drawback people regret most
Choosing a cheaper plan at 65 and wanting Plan G at 75 is often impossible without passing medical underwriting. The open enrollment window is the one time every company must accept you at its standard rates.
What Plan G Actually Costs: Maryland 2027 Premiums
Maryland’s Insurance Administration publishes Medigap premiums twice a year. Its guide for rates as of January 1, 2027 shows how wide the price range is for one identical plan.
| Company (MD, male 65, non-tobacco) | Plan G | Plan N | High-deductible G |
|---|---|---|---|
| Humana Benefit Plan of Illinois (preferred) | $246 | $178 | $67 |
| American Benefit Life | $253 | $185 | Not listed |
| Federal Life | $276 | $199 | Not listed |
| Aetna Health Insurance (preferred) | $300 | $194 | $54 |
| GPM Health and Life | $430 | $356 | Not listed |
Monthly premiums, rounded. Source: Maryland Insurance Administration Medicare Supplement Rate Guide, premiums as of January 1, 2027. Most listed companies use attained-age pricing. Your rate depends on age, sex, tobacco use and health.
The same Plan G ran from $246 to $430 a month in one state, a difference of $2,208 a year for identical benefits. That spread is the strongest argument against buying on brand name alone.
Plan G Quotes
Call a Licensed Agent Now
See Plan G, Plan N and high-deductible G prices from several insurance companies.
No obligation to enroll
Plan G vs Plan N vs High-Deductible G: The Math
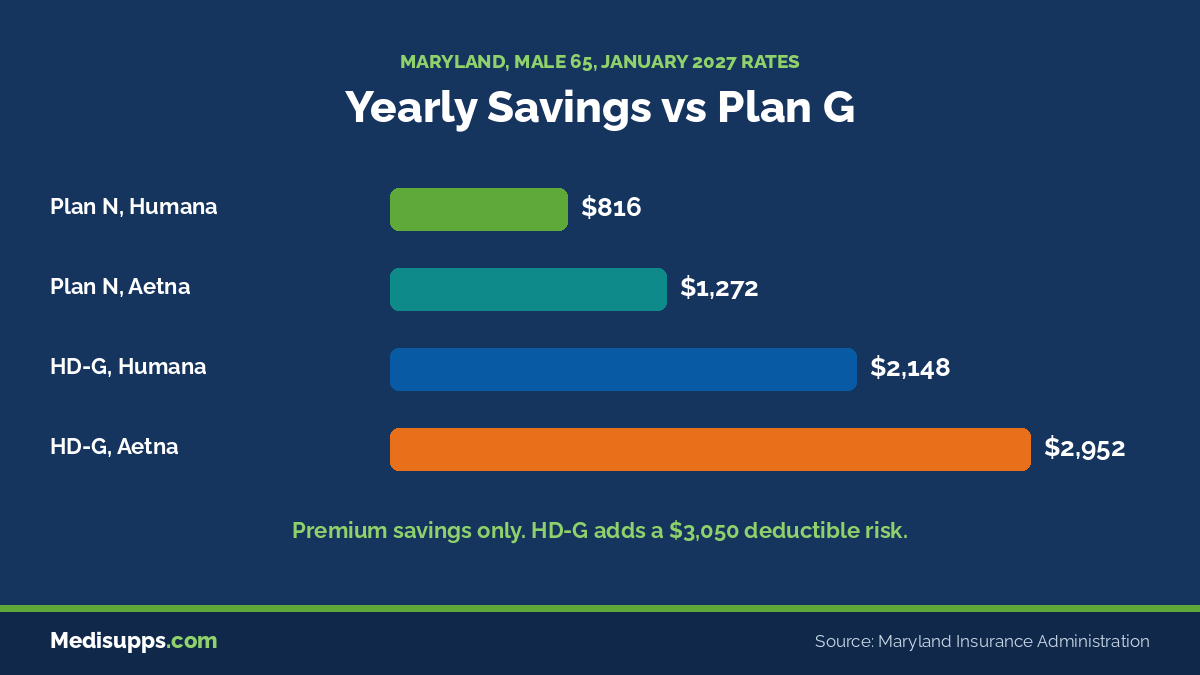
Using the Maryland premiums above and the 2027 Medicare figures, here is what each plan costs at two companies, first in premium alone and then in a year with heavy medical use.
| Plan, company | Yearly premium | Worst-case covered-care year |
|---|---|---|
| Plan G, Humana | $2,952 | $3,244 (premium + $292) |
| Plan N, Humana | $2,136 | $2,428 plus copays and excess charges |
| High-deductible G, Humana | $804 | $3,854 (premium + $3,050) |
| Plan G, Aetna | $3,600 | $3,892 |
| High-deductible G, Aetna | $648 | $3,698 |
Our calculation from the Maryland January 2027 rate guide (monthly x 12) and CMS 2027 amounts: $292 Part B deductible, $3,050 high-deductible G deductible.
What the math shows
At Humana, Plan N saves $816 a year, which covers about 40 office copays of $20. At Aetna, high-deductible G’s worst-case year is actually $194 cheaper than Plan G’s, so the right choice depends on the price gap at each company.
For a deeper comparison, read Medicare Plan N vs Plan G and our guide to high-deductible Plan G.

Before you buy
A premium quote covers only the first year. Ask whether the policy is priced on attained age, issue age or community rating, since that method decides how fast the same Plan G grows more expensive as the years pass.
Russell Noga, Licensed Insurance Agent
Who Plan G Fits Best
Compare Plan G with every other letter in our Medicare Supplement plans section, or go back to the Medisupps.com home page.
Plan G, N and HD-G
Put Three Medigap Options Side by Side
Compare premiums for the plans most new enrollees choose.
Rates and plan availability vary by state, age and insurance company.
Medicare Plan G Pros and Cons: Questions We Hear Most
➤ What is the biggest disadvantage of Plan G?
Cost. Plan G usually has a higher premium than Plan N or high-deductible G, and you pay it every month whether you use care or not.
➤ Is Plan G better than Plan F?
Plan F also pays the Part B deductible, but it is closed to anyone who became eligible for Medicare on or after January 1, 2020. For newer enrollees, Plan G is the most complete option.
➤ Does Plan G cover prescriptions?
No. Medigap plans sold today do not include drug coverage, so most people add a separate Part D plan.
➤ Can I switch from Plan G to Plan N later to save money?
Often, but in most states the new company can ask health questions unless you have a guaranteed issue right or live in a state with a birthday or anniversary rule.
➤ Do Plan G premiums go up every year?
Most do. Companies file rate increases with state regulators, and attained-age policies also rise as you get older.
➤ Does Plan G have a network?
No. You can see any doctor or hospital in the U.S. that accepts Medicare, with no referrals required.
➤ Is Plan G worth it for a healthy 65-year-old?
It can be, because it locks in full coverage while you can buy it without health questions. Compare the yearly premium difference with Plan N and high-deductible G in your ZIP code before deciding.
➤ Does Plan G pay Part B excess charges?
Yes. That is one of the main differences from Plan N, which leaves excess charges to you.
Talk It Through
Call a Licensed Agent Now
A licensed agent can weigh Plan G’s pros and cons against your local prices.
No obligation to enroll
Medisupps.com is operated by ZRN Health & Financial Services, LLC, a licensed insurance agency based in Austin, Texas. We are not connected with or endorsed by the U.S. government or the federal Medicare program. Premiums are examples only; your rate depends on your age, ZIP code, tobacco use and the insurance company.
Russell Noga is the CEO and Medicare editor of Medisupps.com. His 15 years of experience in the Medicare insurance market includes being a licensed Medicare insurance broker in all 50 states. He is frequently featured as a featured as a keynote Medicare event speaker, has authored hundreds of Medicare content pages, and hosts the very popular Medisupps.com Medicare Youtube channel. His expertise includes Medicare, Medigap insurance, Medicare Advantage plans, and Medicare Part D.